American Pacific Mortgage

American Pacific Mortgage
Showing posts with label homeloans. Show all posts

Wednesday, December 13, 2023

YEAR END REFLECTIONS - GOOD RIDDANCE 2023!

Well, what a year we’ve had!  As 2023 winds up, we are glad to see her in the rear view mirror!  2024 should bring lower rates and more inventory for home buyers to choose from! 

MARKET AND RATES

While the volume of home sales hit a record low this year, prices have continued to rise in most of Southern California.  If you are planning a home purchase, we strongly recommend that you move sooner than later.  We will experience a buying frenzy as soon as rates get a bit lower (they have already softened in the last month) and buyers will come off the sidelines in droves.  With lower rates, more homeowners will list their homes.  One might think more homes on the market would mean prices will drop.  But, there is so much pent up demand there is no indication that home prices will come down.  Don’t delay!

A REAL STORY  

In the last week, two different clients called us, ready to make an offer on a property.  They had gone to an open house, and loved the home.  However, in both cases, they were not yet pre-approved.  We had not had time to collect data and strategize with them.   By the time they provided us the documentation required (income and asset information primarily) so we could pull a credit report and run automated underwriting, the home was already in escrow and pending close.  Get Pre-Approved ahead of time!  Don’t delay and miss out on your dream home!  We work with some buyers over a year to prep ahead of time.

GOOD NEWS FOR 2-4 UNITS

Until last month, buyers or owners of 2-4 units needed to have a minimum of 15% down or more.  The Agencies (FNMA and FREDDIE) have reduced the minimum down payment required for 2-4 unit properties to 5%, so long as one of the units is owner-occupied.  This is fabulous news.  Remember, you will receive credit for 75% of the imputed rental income for the other units, so this actually helps qualify for a purchase!!

NEW INCREASED CONFORMING LOAN LIMITS

Conforming loans meet FNMA and FHLMC guidelines.  These guidelines are more lenient vs. Jumbo loan programs, so the rise in the loan limits is good news.  Many counties throughout California have different loan limits-- so we always need to check, depending on property address. 

$1,149,825 – LA and Orange County; San Diego is slightly lower.

$766,550 – Riverside and San Bernardino

TAX RETURN REMINDER

Please don’t file your federal returns for 2023 until we can review them, if you plan to buy or refi next year.  This can make or break a successful transaction.

MERRY CHRISTMAS and HAPPY HANNUKAH TO ALL.  REMEMBER TO BE SAFE, BE KIND, AND CHERISH YOUR LOVED ONES.  WE LOST A DEAR FRIEND THIS MONTH.

As always call us with any questions or concerns you may have.

Karen, Katie and Stephanie


Wednesday, March 9, 2022

First COVID, Now A War in Ukraine?

RATES

When clients ask me where rates are heading (nearly every day), I always point out that since we have an international economy today, events around the world can and do affect interest rates here in the US.   Case in point, the markets are currently experiencing dramatic volatility and rates have dropped a bit after a rapid climb in the first Q this year.  How long will it last?  No one can guarantee they will remain on a downward trend, as they have been up and down over the last week.  The bottom line is we can only move forward knowing that eventually rates will continue to rise.  There is nothing like the thrill of receiving three or more reprice notifications during one day!  Up by .25%, down .375%. Yikes!!

The war is having effects in multiple areas including interest rates;  the stock market;  oil prices (as we all can see at the gas pump) and on many other consumer products, as the supply chain is further impacted.   At this juncture no one can predict how long this will last. Only that the poor citizens of Ukraine are feeling much worse pain.

VALUES

Home prices across the country rose last year by an astounding 19%.  In both Los Angeles and Orange Counties, the median home price was $950,000 for the month of January.  Crazy!  Most homeowners have a tremendous amount of equity to play with, whether to pull out cash for upgrades or remodeling, adding a new pool, or to buy another home.  The problem is the short supply of new housing.  I looked at a few Open Houses the past weekend.  It was so nice to actually go to an Open House!   One property was a total teardown with incredible ocean views in the hills of San Clemente, listed at only $1.45 million.  WOW.  We figured it would take at least a $2 million budget to get it to a livable condition.

The lack of inventory is a major contributor to rising home prices.  Our inventory in Southern California is at an all-time low.  That is right, I said an ALL-TIME low.  In some areas condo values rose more quickly than did values of single-family residences, which is an anomaly. This is likely due to higher demand at the lower price levels pushing up those values.

DID YOU KNOW? 

HUD came out with Reverse Loans for purchase with the HECM program in 2009.  I closed a home purchase in March of 2009 with a Reverse loan, for what may have been the first in California.

FUN STUFF

Steve and I began golfing almost every weekend during COVID as one of the few activities we could safely participate in.  While I still don’t have a handicap, I want to report that during our recent golf scramble with 15 couples from our yacht club, we used several of my drives, fairway shots and putts.  YESSSS!

Speaking of the yacht club, things are beginning to return to normalcy with a Mardi Gras bash, weekend brunches and even prime rib night.  Next up:  A weekend cruise to Newport to visit with other yacht clubs.   Steve enjoys crewing on a couple of different boats for the racing events which happen most weekends.  Then we have the Newport to Ensenada race, otherwise known as N2E in April.  I will go down on a tour bus and meet the racers when they get in.  You never know how long the race will take as it all depends on the wind conditions.

Please remember, Life is Good!  And don’t hesitate to call us with any questions you may have.

Thursday, February 3, 2022

February 2022

Groundhog day has come and gone, and here in Southern California we noted a shadow, predicting more wintry weather.  At least we are not dealing with blizzards like much of the country!

INTEREST RATES

It is definitely feeling wintry when looking at the interest rate climate.  Rates continue to rise and we are also facing new “Loan Level Pricing Adjustments” for high-balance conforming loans (those over $647K) as well as big pricing adjustments for second homes. 

The rise in interest rates have a great effect on affordability as you can see here:

$700,000 loan at 3.5% carries a Principal and Interest payment of $3143. The same $700,000 loan at 4% carries a payment of $3342.  This $200/month difference can make or break it for some buyers/homeowners.  There is no time to delay in moving forward with a home purchase or refinance.  As rates continue to rise it may influence home prices/values, but for now inventory remains so low that there is no relief in sight from rising prices.

TAX TIME

Please have your Home Loan Officer review your draft returns prior to filing if you are self-employed or own rental real estate.  I cannot stress the importance of this enough. We frequently see tax returns for self-employed individuals as well as corporate returns where a small adjustment here or there can make an enormous difference in the income used to qualify for a home loan.  If you are planning to buy or refinance in the coming year, make this a priority.

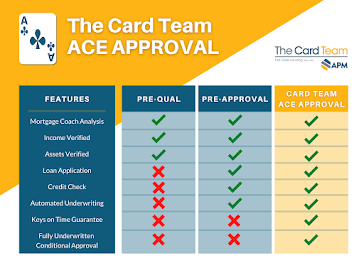
 PREQUAL vs. PRE-APPROVAL vs. ACE APPROVAL

There are a lot of misconceptions about these terms when a buyer is making an offer to purchase a home.  As Real Estate Agents know, sometimes “prequal” or “pre-approval” letters are not worth the paper they are printed on.  A “Prequal” is typically based on a phone conversation providing verbal information on income and assets.  I have yet to speak with a self-employed individual who accurately reported their income to me verbally.  A “Pre-approval” is based on income and asset documentation provided to your lender, along with a completed loan application and a credit pull.  With these the lender can run automated underwriting – universally used today – and provide an automated underwriting approval. 

An ACE approval is a full underwriting approval subject to only identifying a property and obtaining an appraisal. Either the human underwriter or the Artificial Intelligence underwriter, that actually reads the documentation in the file, has reviewed everything and approved the borrower for a specific loan amount.  We strongly suggest obtaining an ACE approval (otherwise known in the industry as a TBD approval) given current market conditions.  It is so competitive!  With an ACE approval we can shorten contingency periods or remove them altogether, offer shorter escrow periods, and even waive appraisal contingencies depending on the borrower.  Why did we name it the ACE approval?  We are the CARD TEAM after all-- and hold all the Aces!

REVERSE LOANS

Baby Boomers are retiring right and left.  By the year 2030 all Baby Boomers will have turned 65.  Whenever we work with clients approaching retirement or already retired, we always show them various financing options, to include reverse loans.  These are helpful in a number of ways, including improving monthly cash flow by eliminating the mortgage payment;  or providing an income stream in various forms such as a line of credit or fixed monthly distributions.  They are also a useful tool for financial planners to use in down market years (to avoid liquidating pre-tax funds which is costly) since the income from a reverse loan is tax free.

There are many misconceptions still floating around about reverse loans: 

1.     The bank does not own the home or take title after the borrower passes.  The home goes to the heirs.  The owner remains on title throughout the life of the loan.

2.      You can’t outlive your reverse loan.  The only event of default is failure to pay your taxes, insurance or permanent move-out.  You must live in the property. The loan is non-recourse and there is no time limit involved.

3.      A reverse loan does not affect Social Security or Medicare.

4.      Reverse loans are no more expensive than a typical FHA loan, and with jumbo reverse loans the costs are similar to a regular refinance. 

As always, please reach out to us with any questions or concerns.  We are here to be a resource to our clients.

Thursday, January 6, 2022

January 2022

Welcome to 2022! WOW! What a year 2021 was! We would like to wish everyone a Happy New Year and update you on the Mortgage market with news and tips on financing for purchases as well as refinances. 

CONFORMING LOAN LIMITS INCREASE! 

The new limit for conforming loans (FANNIE and FREDDIE) has been increased to $647,200 across the nation for a one-unit home. However, in high-cost areas such as LA and Orange Counties, the high balance limit is $970,800. San Diego has a slightly lower high balance limit, and Riverside and other counties are limited to $647K. What does this mean? Conforming loans have more lenient guidelines for loan approval vs. “Jumbo” loan programs. Great news all around! 

RATES 

Interest rates have begun their inevitable rise from the lows of 2020-2021. It could not last forever, and as the Fed eases up on the buying spree of mortgage-backed securities, we are seeing rates rise. In addition, inflation has kicked in and the economy is improving. What this means for home buyers is there is no time to spare in getting into the housing market or making that “move up.” Interest rates have a far greater effect on affordability than rising home prices. Our advice is to get in while the getting is good! 

HOME VALUES 

Nationwide home prices rose by an average of 19.5% last year. There is a huge shortage of housing across the country. Right now inventory in Orange County is at an all-time low. This means the bidding wars for property will continue. Don’t be fooled into thinking that with interest rates rising, home prices will come down. They won’t -- as there is no inventory! It is a GREAT time to sell! 

LOAN UNDERWRITING AND APPROVAL 

It is all-important to be fully approved for a loan BEFORE you get out and make any offers, so you can be as competitive as possible with shorter time frames for closing, and fewer contingencies. We frequently see buyers experiencing “offer fatigue” after making multiple offers and losing out to a higher bidder. This is why it is best to be as competitive as possible with a full loan approval and shorter or no contingencies. 

Anyone who is self-employed and has an S-Corp or C-Corp should have their draft returns reviewed by their lender PRIOR to filing, if you intend to make a home purchase or refinance this year. We frequently work with tax preparers and CPAs to be sure returns accurately reflect income and are not purposely attempting to minimize the income tax burden. This can kill a loan approval! 

Underwriting guidelines continue to be quite stringent, especially when it comes to self-employeds. Recent business bank statements and up-to-date P&Ls are required for all self-employed borrowers. 

The use of gift funds for down payments, especially with first-time home buyers is increasing. This requires a gift letter and asset statements snapshot from the donor. We are often asked whether this is taxable to the donor or recipient. The short answer is no, but Form 709 should be filed with the IRS annually if the gift exceeds the exempt limit of $16,000 per individual. However it is noteworthy that the current lifetime exclusion is over $12 million per person, so most of us don’t need to worry about the gift tax. We might wish we did! 

ESTATE PLANNING 

We are passionate about estate planning and urge all our client to put a plan in place to care for minor children, and to protect your assets from going through a very costly probate. This is something that should not be put off if you care for your family members. Property and most assets should be titled in a living trust, so your estate is not “probated.” Considering property values in California many homeowners have quite substantial assets. We can refer clients to trusted professionals to assist. 

Please reach out to our team with any questions or concerns you may have. We are here to be a resource for you! 

Karen, Katie and Stephanie