American Pacific Mortgage

American Pacific Mortgage
Showing posts with label #rates. Show all posts

Saturday, July 11, 2026

What Buyers are Really Asking; Divorce & Life Transitions

Every week I spend time researching the questions buyers are asking Google and ChatGPT before they ever contact a Realtor or lender. My goal is to keep you informed about what your clients are thinking—and to help you answer their questions with confidence.

This Week's Focus: Divorce & Life Transitions

Divorce is one of life's most challenging transitions, and for many people, their home is their largest asset. Unfortunately, one of the biggest mistakes I see is waiting until the divorce is finalized before discussing mortgage financing.

By then, some opportunities may already have been lost.

Here are some of the questions borrowers are asking AI this week:

"Can I keep the house after my divorce?"

Possibly—but the answer depends on much more than simply wanting to keep it.

Can the remaining spouse qualify on their own? Will support income be received, and can it be used for qualification? Is refinancing necessary? These questions should be addressed early in the process, not after the settlement agreement has been signed.

"Does the divorce decree remove me from the mortgage?"

No.

A divorce decree determines who is responsible for the home as part of the legal settlement, but it does not automatically remove a borrower from the mortgage loan. In many cases, refinancing or another approved solution is needed before one spouse is released from liability.  However, this loan will not be considered for the spouse who is  not responsible for the loan, when purchasing a new home.

"Can support income help me qualify?"

Often, yes.

Depending on the loan program and documentation, alimony or child support income may be considered for qualification. The timing, documentation, and history of those payments can make a significant difference.  Typically six months of receipt is required in order to use it.

"Can I buy another home before my divorce is final?"

Sometimes.

Every situation is unique. Factors such as qualifying income, existing mortgage obligations, the terms of the separation agreement, and available assets all play an important role. This is one reason it's so valuable to begin planning early.  I’ve handled these situations before, and so long as there is a court approved property division agreement, it is possible.

Karen's Loan Desk

One of the most rewarding parts of my job is helping clients through major life transitions.

I've worked with many individuals before, during, and after a divorce. While every situation is different, I've learned that the earlier we have the mortgage conversation, the more options we usually have.

Sometimes it's not about finding a loan—it's about creating a strategy that supports the best possible outcome for everyone involved.

The takeaway?

Don't wait until the divorce is final to discuss financing. A conversation early in the process can help avoid surprises and preserve valuable options.

AI Prompt of the Week for Realtors

One of the best ways to use ChatGPT is to communicate with empathy while providing helpful information. Copy and paste this prompt:

Act as an experienced Orange County Realtor. Write a compassionate email to someone going through a divorce who may be concerned about their housing options. The email should be reassuring, educational, and non-salesy. Explain why it's important to speak with a mortgage professional early in the process to understand financing options before major decisions are finalized. End with a gentle invitation to ask questions. Keep it under 300 words.

Realtor Tip of the Week

If you have clients navigating a divorce, separation, or another major life transition, let's have a conversation before the property is listed, refinanced, or awarded in the settlement.

A simple planning session can help answer important questions, identify potential challenges, and give your clients greater confidence as they move forward.

As always, I'm happy to review any scenario, answer questions, or help develop a financing strategy that best serves your clients.

Have a wonderful weekend!

 Karen and the Card Team

Tuesday, June 2, 2026

Longer Days and Sunshine: It's Summer!

The longest day of the year is almost upon us. It's my favorite time of year—the sunshine, warm weather, and longer evenings spent outdoors. Of course, it's also the beginning of the gradual march toward shorter days. ☹

The kids are out of school and fully immersed in summer activities. My grandkids are keeping busy with everything from sailing, Junior Guards, and swimming to baseball camp, theater programs, and dance camps. Summer in Southern California really is a special time of year.  I'm keeping busy with home buyers and refiances, with a little vacation sprinkled in!  I'll update you next month....

RATE UPDATE

Mortgage rates have remained relatively stable over the past several months despite ongoing economic uncertainty. Inflation appears to be moderating, but global events, geopolitical tensions, energy prices, and government policy continue to create volatility in the financial markets.

While no one can accurately predict where rates will be six months from now, most analysts expect rates to remain within a relatively narrow range through the balance of the year. If you're considering purchasing a home or refinancing, it may make more sense to focus on whether the move benefits your financial goals rather than trying to perfectly time the market.

REAL ESTATE MARKET

The Orange County housing market appears to be moving toward a more balanced environment, with some areas beginning to favor buyers. Inventory has increased from the extremely low levels we've experienced over the past few years, giving buyers more choices and negotiating power.

We're seeing more sellers offer concessions, including interest rate buydowns, credits toward closing costs, repair allowances, and other incentives to help facilitate a sale.

While median home prices in Orange County remain strong, it's important to note that a significant number of luxury and multi-million-dollar transactions have helped support those statistics. In many neighborhoods, price appreciation has slowed and homes are taking a bit longer to sell than they did during the frenzy of recent years.

CREDIT SCORES & MORTGAGE QUALIFYING

Many consumers are surprised to learn there isn't just one credit score. Different industries use different scoring models. Auto lenders, credit card companies, insurance providers, and mortgage lenders may all evaluate credit differently.

The mortgage industry is preparing to transition to newer credit scoring models that may provide a more complete picture of a borrower's creditworthiness. This could be particularly helpful for borrowers who have limited traditional credit histories but have otherwise demonstrated responsible financial habits.

If you're curious about your credit profile or wondering how today's scoring models affect your ability to qualify, I'd be happy to review your situation.

HELOCs ARE MAKING A COMEBACK

We're helping more homeowners access their equity through Home Equity Lines of Credit (HELOCs). Homeowners today are sitting on record amounts of equity, and many are using HELOCs strategically for:

• Home improvements and renovations
• Debt consolidation
• Down payments on second homes or investment properties
• Educational expenses
• Emergency reserves and financial flexibility

A HELOC isn't right for everyone, but it can be an excellent financial tool when used appropriately.

CALIFORNIA INSURANCE UPDATE

Homeowners insurance continues to be a challenge throughout California. Many homeowners have experienced premium increases, policy non-renewals, or difficulty finding coverage altogether. Areas with wildfire exposure have been particularly affected, but the impact is being felt across much of the state.

The good news is that new insurance carriers are beginning to re-enter the California market, creating additional options for homeowners. While premiums remain higher than many of us would like, there are often alternatives available that can help reduce costs or improve coverage.

If you have questions about your current insurance situation, are purchasing a home, or simply want a second opinion on your coverage options, I have relationships with several excellent insurance professionals and would be happy to connect you with someone who can help.

SUMMER FUN ALONG THE COAST

Summer is officially in full swing along the Southern California coast. From outdoor concerts and movies in the park to festivals, farmers markets, harbor events, and beach activities, there's no shortage of things to do from Seal Beach to San Clemente.

If you're looking for ideas for family activities, date nights, local events, or hidden gems around Orange County, reach out. I'm always happy to share some of my favorites.

As always, thank you for your trust, referrals, and friendship. If you have questions about the market, mortgage financing, or your home's value, I'm just a phone call away.

Have a wonderful summer!

Karen Card

Tuesday, May 14, 2024

FICO SCORING SECRETS & MARKET UPDATES

Market Update

More Inventory, and even more buyers!!!

The spring selling season is here!  The seller’s market continues with demand outpacing inventory.  And, prices continue to rise despite stubborn interest rates. We are seeing more competitive bidding again for many homes.  In order to stand out, buyers must be fully pre-approved and ready to act swiftly.

Rates are high compared to the pandemic period, but are still running close to historical averages.  Expert guidance is key to navigating the mortgage process, especially for first time homebuyers.  Be sure to work with a knowledgeable and experienced lender to streamline the process and ensure a successful close.

Here is the current conundrum regarding rates:  Prices are high, CPI is high, and inflation is higher than the Fed wants.  The Feds will apparently only reduce rates when CPI falls.  Which will only happen when home price appreciation cools.  Which will only happen when there is a sustained increase in housing inventory.  Which will only happen when rates fall.  And, back to the beginning.


FICO SCORE HELPFUL HINTS

When planning for a home loan, whether a purchase or a refinance, it is paramount to understand the factors that influence your FICO score.  And, remember there are different scoring models. Clients may tell me what their FICO score is, but when I pull a Tri-Merge from Experian, Transunion and Equifax, which is required for a mortgage loan, the scores are quite different. 

1.      Payment History – Late payments, especially on any mortgage are a critical negative factor.

2.      Credit Utilization – Keep balances to less than 30% of credit available; this is typically the most common issue affecting FICO scores we see

3.      Length of Credit history – the longer you have had credit, the better.  And, being added as an Authorized User to a relative’s long-standing account may help, check with us first!

4.      Credit mix – Installment loans (auto loans) or leases help your score when coupled with revolving credit. And, have at least two or three revolving credit accounts.

5.      Inquiries – typically these have the least effect on your score although consumers believe otherwise.

We frequently work with clients to assist them with credit repair.  Here are some of the most common questions we hear:

1.      Should I pay off my credit cards and/or car loan?  Not necessarily, unless they are affecting your debt-to-income ratio.  You don’t need to be debt-free to qualify for a home loan.  And sometimes it is best to have a small balance on some accounts.

2.      Should I close my credit cards that I don’t use anymore?  After all, I’ve paid them off.  NO!  This will have a negative effect on your FICO score.  The more unused credit you have, the better!!!! Never close an account.

3.      Can I apply for a car loan at a number of places to find the best rate?  NO!  Too many inquiries at one time will temporarily drop your score.

Always discuss any possible changes to your credit cards or loans with your loan officer first.

We are here to help and be your resource!

Karen, Katie and Stephanie

Wednesday, October 4, 2023

ADVERSITY, OPPORTUNITY AND FAST CASH!


MARKET UPDATE - ADVERSITY

The latest news for multi-family housing is developers have slowed/stopped new construction.  This is primarily due to higher interest rates coupled with greater difficulty qualifying for loans.  This will translate into higher rents, particularly in the coastal areas of California where housing is already in short supply and high demand.

Translation:  Prospective buyers should not wait for rates or prices to come down, as neither is likely in the next 12 months.  No one anticipates home values to decrease.

OPPORTUNITIES

We are offering a personal loan program – NOT a Mortgage loan – for auto loans, remodels, swimming pools, debt consolidation, recreation and more.  This is not recorded on your home and has no effect on the low rate first mortgage most of our clients have. The turn time on these loans is extremely short, even overnight, and offers a quick and easy way to access fast cash.

Loan amounts can vary from $5,000 to $100,000.  Loans are underwritten based on income, assets, and credit.  The process is completely digital and there are no up-front fees or prepayment penalties.

Click here for the link to a quick qualification process:  Personal Loan Link

REMINDERS

Real estate taxes are coming due, and must be paid by December 10th to avoid penalties  The second half taxes are due by April 10th.  Such great timing for Christmas and tax time, huh?

Self-employed borrowers should have their taxes reviewed by us prior to filing if they are considering making a home purchase or refinance in the next two years.  Writing off too many expenses can kill a home purchase or refi, unless you want to use a bank statement loan which carries a higher rate.

PERSONAL UPDATES

I’m writing this from Madera (just north of Fresno)  where I am temporarily staying with my sister who suffered a stroke.  My sister lives alone and we were extremely lucky her daughter sounded the alarm when she could not contact her one morning. 


She is improving daily, and we expect a full recovery.  This has been a big wakeup call and reminder to be grateful every day, keep your loved ones close, always do your best and be kind to all.  And, take good care of your health.

As always, call us with any questions or concerns.


Monday, August 7, 2023

HOT, MUGGY HEAT WAVE AND RATE HIKES

 RATE OUTLOOK

The recent heat wave has brought not only higher temperatures across the country but also higher interest rates.  I guess you could say “careful what you wish for”…we were so tired of the cold, but we were not looking forward to a rate rise.

With the recent Fed rate hike of another .25%, up to 5.5%, it brought Prime Rate to 8.5%.  This is the highest Prime Rate since 1991.  What is Prime Rate?  It is the rate generally used by banks to lend to customers with good credit and is oftentimes used as an index for floating rate loans such as a Home Equity Line of Credit.

Mortgage rates have risen as a result and should level off as we don’t anticipate any more Fed Funds rate hikes.  Recession hopes (or fears) are lessening and a soft landing seems to be on the horizon.  What does that mean for interest rates?  They are likely to ease more slowly than we anticipated earlier in the year.  They will eventually come down, but it may take longer so don’t hold your breath for rates in the 3’s or 4’s again. 

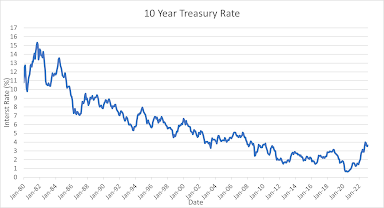
Essentially, we’ve just about hit the average mortgage rates for the last 50 years.  Back when I had to walk miles through the snow to get to school, they were almost identical to today before they shot up in the early 80’s (18%!) and proceeded to generally decline over time from that point until July of 2021.


PROPETY VALUES

While low inventory continues, there is little downward pressure on home prices.  It is now apparent that few homeowners with a rate in the 2’s or 3’s have any motivation to sell, unless they are moving out of state or are experiencing a life change-- (job change, divorce, or death) There are rumors of stagnation in the “luxury” market, i.e. slower pace of selling for homes over $2 to $3 Million. Home prices have risen as of the latest sales in most Southern California markets.

CONSTRUCTION LOANS

Did you know…we have a construction lending department that can provide construction loans for rehab purposes as well as new construction.  They are a bit more complicated as funds are doled out as work is completed and invoices provided, and there is a lot of up-front planning that takes place such as approval of architectural plans, appraisal, contractor, etc.

BEACH TIME and FAMILY UPDATES – Sailing and Swimming!

We recently spent four days camping in Carpinteria on the beach.  We had most of the family there, which was a real treat.  Barbeques, sitting around the campfire, playing in the ocean and on the sand, and taking beach walks in the morning was all part of the experience. We had to watch for the raccoons who were voracious and got away with an entire carton of eggs one evening in our presence!  They are sneaky and fast!

Grandson Theo in San Diego has been killing it in his sailing races.  He just competed in the Jr. National Sabot Championships in Newport at NHYC and came in 19th overall out of 150 sailors.  He was also in the top 10 in the preliminaries.  WOW!  WAY TO GO THEO.

My granddaughter Kay (AKA Karen, my namesake) is age 6 and just finished her very first swim meet and won both her events – the 25 free and 25 fly.  Big surprise as her mama, my partner Katie, was a very competitive swimmer through high school, although college was all about Water Polo. Go Bears!

As always, we are here to help with any questions! 


Monday, July 10, 2023

SUMMER FINALLY ARRIVES FOR THE 4TH!

We hope everyone had a Happy and Safe 4th of July!  Ours was eventful with visiting children, Water Wars in the Harbor, and a traditional barbeque crowned by the fireworks in Dana Point.

INTEREST RATES

Interest rates have risen to recent highs, due to continued new job growth, dropping unemployment, and the Fed’s news that they will yet again raise rates to slow inflation further.  Although inflation has lowered to 4%, it has not yet hit the desired target of 2 to 3%. 

Most economists do expect rates to come down in the next six months, but they are not expecting as steep a drop as before.  Our advice is to prepare for the “new normal.”    Once rates stabilize, we will likely see rates in the 5’s for some time.

MARKET UPDATE

Home prices are very slightly off their highs of last May.  Orange county still has a $1 million median price, down from $1.05 million, while LA county has a median of $800K, down from the $860K high a year ago.  And, homes are again selling over list price!

The biggest issue continues to be a very low sales volume, which can primarily be attributed to the paucity of listings.  Of course, interest rates play into the volume of sales, but there are so few listings there is little downward pressure on home prices, if any.

MOVING OUT OF STATE?

We are part of a large network of loan officers licensed in all states in the country, save New York.  We can assist our clients with financing when moving or buying a second home out of the state of California.

The most common states to move to?  Nevada, Arizona, Oregon, Idaho, and Texas.  Lower taxes seem to be a large part of the equation!  There is also a migration out of cities and into suburban or rural environments.

THIS AND THAT

We continued our holiday celebration last Wednesday with a pool party with dear friends.  It was lovely weather for the pool, and even better times with old friends!  And, my sister joined me for a long weekend to visit and attend the art festivals in Laguna!  She is a new member of the Madera County Grand Jury.  Pretty impressive stuff!


Monday, September 12, 2022

THAT WAS FAST! Summer is officially over

No more white shoes, white pants or dresses, right?  Although we think that idea is a bit out of date today, at the Yacht Club white pants are not de rigueur after Labor Day.  Acting as the “Officers of the Deck” this week, we were asked to dress in formal yacht club attire which includes white or blue shirts, grey or khaki pants and navy jackets emblazoned with the Club Bullion.

Now, down to business:

Housing Market Correction

The experts are all weighing in on the likelihood of a “correction” to the housing market. Will prices come down?  There is a good deal of downward pressure on prices.  We may see a swing closer to a buyers’ market in the near future.  But remember, inventory is still extremely low.  No “crash” is in sight.  All the factors make it highly unlikely.

Rates

Up, down and sideways. Last week they hit an average of 6% which is the highest since 2008. However, a graph of average interest rates over the last 50 years in the US shows we are still quite near the low end.  It has been the sudden doubling of rates over the last 18 months that has buyers pushing the pause button.  Affordability has decreased with the rate rise.  Loan applications are down significantly which also means there is less competition out there for willing buyers.

Refinance activity particularly has slowed significantly, and is providing only 30% of current total loan volume.

Conforming Loan Limit Increases

The conforming loan limit, which includes both Fannie Mae and Freddie Mac loans, will rise effective January 1st but many lenders, including APM are already accepting rate locks for conforming loans up to a $715,000 loan amount. The actual new limit could be higher, but most agree that $715K is a safe bet.  What does this mean for borrowers?  Conforming loans are easier to qualify for!  Good news all the way around

Down Payment Assistance

No cash for a down payment?  No problem.  We have programs to assist new homebuyers with as little as $500 cash. With a combination of down payment assistance through various programs, coupled with seller credits to offset closing costs, there is almost no cash required to get into a home.  Of course there are income qualification requirements. 

Don't hesitate to reach out to us with questions!  Enjoy the transition to fall, we can't wait to cool off a bit.


Tuesday, February 4, 2020

Rate and Travel Updates

Mortgage rates continue to hover near record lows with the Corona virus taking most of the credit! The market flight to security caused a dip in the stock market which provided a boost to US treasuries.

What does it all mean? Right now is a great time to pull cash out of your home for improvements or remodeling, while rates are low. Home prices have continued to increase, as there isn’t a lot of inventory out there, which means it is a great time to sell if you are so inclined.

If you haven’t refinanced recently you can likely lower your rate and payments, even if you aren’t pulling cash out.

Loan limits have increased again for FNMA, Freddie and FHA/VA loans. The high-cost counties, such as Orange and Los Angeles, are up to $765,500 loan limits… which makes it easier to qualify for mortgage financing.

Reverse loans continue to gain in popularity although I still hear some of the myths repeated, such as “the bank owns your home.” NOT!!!

Please reach out to me or Katie with any questions. We are here to help! Visit our website at www.card-team.com.

FAMILY - TRAVEL

We continue to enjoy spending time with our adult children, grandchildren, and friends. The grandchildren, now numbering five, are ages 7,5,3,2 and 1. We took a camping trip to El Capitan, north of Santa Barbara in September, and most of our crew joined us. The weather cooperated and we had a blast swimming and playing on the beach. I actually tried boogie-boarding for the first time, what a hoot.

November saw us traveling to Maui with friends where we stayed at Ka’anapali. We enjoyed hiking to the blowhole, swimming, snorkeling, and got in a number of scuba dives. We saw more sea turtles than ever before, and had our first sighting of Manta Rays. What a delight! One day we did four dives. Water Warriors!

LITTLE DUME

Steve’s boys played at The Troubador last month and they have released an album. WOW! They are amazing. Just search for Little Dume on Spotify or YouTube to tune in and enjoy! They played earlier in the year at our Yacht Club and were a fabulous success. We hope to host them again there soon.

Here is hoping you all have a wonderful 2020!