American Pacific Mortgage

American Pacific Mortgage
Showing posts with label #homeloans. Show all posts

Monday, August 3, 2026

Dog Days of Summer, Rates and Your Home Equity

 It has been an unquestionably hot summer so far, with no end in sight! Days at the beach or in the pool have provided some of the only respite—along with a cold beverage, perhaps a rosé, a crisp dry white, or an Aperol Spritz. And when I get going on wine, I tend to get a little carried away. 😊

Speaking of wine, we're about to head up to Paso Robles for a little wine tasting, and I'm looking forward to discovering some new Picpouls and Albariños. Yes, Paso has finally caught up and realized its climate is quite friendly to these crisp, mineral-driven whites that are growing in popularity.

Okay, back to business!

The Real Estate Market

The real estate market isn't nearly as hot as the weather.

Mortgage rates have remained stubbornly elevated, and recent geopolitical uncertainty has added another layer of volatility. Meanwhile, affordability continues to be one of the biggest concerns I hear from buyers.

The questions I'm hearing most often are:

"Should I buy now or wait?"

And from homeowners:

"How can I access some of my equity without giving up my low-rate first mortgage?"

Fortunately, there are strategies for both.

Want Your Equity? Meet the HELOC and HELOAN

Homeowners who locked in those wonderful low mortgage rates a few years ago are understandably reluctant to refinance their entire mortgage just to access their equity.

That's where a second mortgage may come in.

A HELOC (Home Equity Line of Credit) is generally a variable-rate line of credit. You can draw funds as needed, repay them, and—during the draw period—typically access the available line again. This can be particularly useful for remodeling projects, unexpected expenses, or situations where you don't need all the money at once.

A HELOAN (Home Equity Loan) is different. It is generally a fixed-rate second mortgage with the proceeds funded at closing. You make payments on that loan separately from your existing first mortgage.

And today's second-mortgage programs aren't necessarily one-size-fits-all.

We have access to some very competitive and interesting options, including:

  • Second mortgages for homeowners who want to preserve a low-rate first mortgage
  • DSCR options for certain rental properties
  • Reverse mortgage second-lien solutions in qualifying circumstances
  • Loan amounts that can reach as high as $4 million, depending on the program and borrower qualifications

Which one makes sense? That depends entirely on what you're trying to accomplish.

Buyers: Let's Solve the PAYMENT Problem

Affordability is absolutely a challenge right now, but that doesn't necessarily mean you should sit on the sidelines.

Rather than focusing exclusively on the interest rate, I like to look at the entire monthly housing expense and ask:

What can we do to make this payment work?

There may be more options than you think.

A seller-paid 2-1 buydown, for example, can substantially reduce the buyer's interest rate and payment during the first two years of the mortgage.

Gift funds from a family member can help with the down payment or closing costs and may reduce the amount that needs to be financed.

And remember, you don't necessarily need 20% down to buy a home. Depending on the loan program and borrower qualifications, down payments can be as low as 3% or 3.5%—and eligible VA borrowers may purchase with 0% down.

Every situation is different. That's where good planning really matters.

Before deciding that you can't afford to buy—or that you need to wait for rates to fall—let's run the numbers and see what's actually possible.

A Real-Life Example

I'm currently working with a family that provides a perfect example of how these strategies can come together.

The parents have built substantial equity in their home, and now they'd like to use some of that equity to help their adult son purchase his first home.

We're looking at the entire picture: how much equity to access, the best way to access it, how much the parents should contribute, and how to structure the son's financing so that his new monthly payment remains comfortable.

I love these transactions because we're not simply arranging a mortgage. We're helping one generation use the wealth they've created through homeownership to give the next generation a head start.

If you've ever thought about helping a child or grandchild purchase a home, let's talk. There may be several ways to structure it.

Don't Forget About 1031 Exchanges

One last reminder for my real estate investors:

Before you sell an investment property, talk to us about a 1031 exchange.

A properly structured 1031 exchange may allow you to defer capital gains taxes by exchanging qualifying investment real estate for another qualifying property.

We have excellent resources for both 1031 exchange advice and accommodation, and timing is critical. The conversation should happen before the sale closes, not afterward.

If you're considering selling an investment property, please call me early in the process so we can connect you with the appropriate professionals.

As Always...

Whether you're thinking about buying, refinancing, accessing equity, helping your children purchase their first home, or simply wondering what your options are in today's market, I'm always happy to talk through the numbers.

Sometimes the answer is a new loan.

Sometimes it's keeping exactly what you have.

The important thing is knowing the difference.

Enjoy the rest of your summer—and I'll report back on the Paso Albariños! 🍷

Karen Card
The Card Team

Saturday, July 11, 2026

What Buyers are Really Asking; Divorce & Life Transitions

Every week I spend time researching the questions buyers are asking Google and ChatGPT before they ever contact a Realtor or lender. My goal is to keep you informed about what your clients are thinking—and to help you answer their questions with confidence.

This Week's Focus: Divorce & Life Transitions

Divorce is one of life's most challenging transitions, and for many people, their home is their largest asset. Unfortunately, one of the biggest mistakes I see is waiting until the divorce is finalized before discussing mortgage financing.

By then, some opportunities may already have been lost.

Here are some of the questions borrowers are asking AI this week:

"Can I keep the house after my divorce?"

Possibly—but the answer depends on much more than simply wanting to keep it.

Can the remaining spouse qualify on their own? Will support income be received, and can it be used for qualification? Is refinancing necessary? These questions should be addressed early in the process, not after the settlement agreement has been signed.

"Does the divorce decree remove me from the mortgage?"

No.

A divorce decree determines who is responsible for the home as part of the legal settlement, but it does not automatically remove a borrower from the mortgage loan. In many cases, refinancing or another approved solution is needed before one spouse is released from liability.  However, this loan will not be considered for the spouse who is  not responsible for the loan, when purchasing a new home.

"Can support income help me qualify?"

Often, yes.

Depending on the loan program and documentation, alimony or child support income may be considered for qualification. The timing, documentation, and history of those payments can make a significant difference.  Typically six months of receipt is required in order to use it.

"Can I buy another home before my divorce is final?"

Sometimes.

Every situation is unique. Factors such as qualifying income, existing mortgage obligations, the terms of the separation agreement, and available assets all play an important role. This is one reason it's so valuable to begin planning early.  I’ve handled these situations before, and so long as there is a court approved property division agreement, it is possible.

Karen's Loan Desk

One of the most rewarding parts of my job is helping clients through major life transitions.

I've worked with many individuals before, during, and after a divorce. While every situation is different, I've learned that the earlier we have the mortgage conversation, the more options we usually have.

Sometimes it's not about finding a loan—it's about creating a strategy that supports the best possible outcome for everyone involved.

The takeaway?

Don't wait until the divorce is final to discuss financing. A conversation early in the process can help avoid surprises and preserve valuable options.

AI Prompt of the Week for Realtors

One of the best ways to use ChatGPT is to communicate with empathy while providing helpful information. Copy and paste this prompt:

Act as an experienced Orange County Realtor. Write a compassionate email to someone going through a divorce who may be concerned about their housing options. The email should be reassuring, educational, and non-salesy. Explain why it's important to speak with a mortgage professional early in the process to understand financing options before major decisions are finalized. End with a gentle invitation to ask questions. Keep it under 300 words.

Realtor Tip of the Week

If you have clients navigating a divorce, separation, or another major life transition, let's have a conversation before the property is listed, refinanced, or awarded in the settlement.

A simple planning session can help answer important questions, identify potential challenges, and give your clients greater confidence as they move forward.

As always, I'm happy to review any scenario, answer questions, or help develop a financing strategy that best serves your clients.

Have a wonderful weekend!

 Karen and the Card Team

Tuesday, May 14, 2024

FICO SCORING SECRETS & MARKET UPDATES

Market Update

More Inventory, and even more buyers!!!

The spring selling season is here!  The seller’s market continues with demand outpacing inventory.  And, prices continue to rise despite stubborn interest rates. We are seeing more competitive bidding again for many homes.  In order to stand out, buyers must be fully pre-approved and ready to act swiftly.

Rates are high compared to the pandemic period, but are still running close to historical averages.  Expert guidance is key to navigating the mortgage process, especially for first time homebuyers.  Be sure to work with a knowledgeable and experienced lender to streamline the process and ensure a successful close.

Here is the current conundrum regarding rates:  Prices are high, CPI is high, and inflation is higher than the Fed wants.  The Feds will apparently only reduce rates when CPI falls.  Which will only happen when home price appreciation cools.  Which will only happen when there is a sustained increase in housing inventory.  Which will only happen when rates fall.  And, back to the beginning.


FICO SCORE HELPFUL HINTS

When planning for a home loan, whether a purchase or a refinance, it is paramount to understand the factors that influence your FICO score.  And, remember there are different scoring models. Clients may tell me what their FICO score is, but when I pull a Tri-Merge from Experian, Transunion and Equifax, which is required for a mortgage loan, the scores are quite different. 

1.      Payment History – Late payments, especially on any mortgage are a critical negative factor.

2.      Credit Utilization – Keep balances to less than 30% of credit available; this is typically the most common issue affecting FICO scores we see

3.      Length of Credit history – the longer you have had credit, the better.  And, being added as an Authorized User to a relative’s long-standing account may help, check with us first!

4.      Credit mix – Installment loans (auto loans) or leases help your score when coupled with revolving credit. And, have at least two or three revolving credit accounts.

5.      Inquiries – typically these have the least effect on your score although consumers believe otherwise.

We frequently work with clients to assist them with credit repair.  Here are some of the most common questions we hear:

1.      Should I pay off my credit cards and/or car loan?  Not necessarily, unless they are affecting your debt-to-income ratio.  You don’t need to be debt-free to qualify for a home loan.  And sometimes it is best to have a small balance on some accounts.

2.      Should I close my credit cards that I don’t use anymore?  After all, I’ve paid them off.  NO!  This will have a negative effect on your FICO score.  The more unused credit you have, the better!!!! Never close an account.

3.      Can I apply for a car loan at a number of places to find the best rate?  NO!  Too many inquiries at one time will temporarily drop your score.

Always discuss any possible changes to your credit cards or loans with your loan officer first.

We are here to help and be your resource!

Karen, Katie and Stephanie

Wednesday, October 4, 2023

ADVERSITY, OPPORTUNITY AND FAST CASH!


MARKET UPDATE - ADVERSITY

The latest news for multi-family housing is developers have slowed/stopped new construction.  This is primarily due to higher interest rates coupled with greater difficulty qualifying for loans.  This will translate into higher rents, particularly in the coastal areas of California where housing is already in short supply and high demand.

Translation:  Prospective buyers should not wait for rates or prices to come down, as neither is likely in the next 12 months.  No one anticipates home values to decrease.

OPPORTUNITIES

We are offering a personal loan program – NOT a Mortgage loan – for auto loans, remodels, swimming pools, debt consolidation, recreation and more.  This is not recorded on your home and has no effect on the low rate first mortgage most of our clients have. The turn time on these loans is extremely short, even overnight, and offers a quick and easy way to access fast cash.

Loan amounts can vary from $5,000 to $100,000.  Loans are underwritten based on income, assets, and credit.  The process is completely digital and there are no up-front fees or prepayment penalties.

Click here for the link to a quick qualification process:  Personal Loan Link

REMINDERS

Real estate taxes are coming due, and must be paid by December 10th to avoid penalties  The second half taxes are due by April 10th.  Such great timing for Christmas and tax time, huh?

Self-employed borrowers should have their taxes reviewed by us prior to filing if they are considering making a home purchase or refinance in the next two years.  Writing off too many expenses can kill a home purchase or refi, unless you want to use a bank statement loan which carries a higher rate.

PERSONAL UPDATES

I’m writing this from Madera (just north of Fresno)  where I am temporarily staying with my sister who suffered a stroke.  My sister lives alone and we were extremely lucky her daughter sounded the alarm when she could not contact her one morning. 


She is improving daily, and we expect a full recovery.  This has been a big wakeup call and reminder to be grateful every day, keep your loved ones close, always do your best and be kind to all.  And, take good care of your health.

As always, call us with any questions or concerns.


Monday, August 7, 2023

HOT, MUGGY HEAT WAVE AND RATE HIKES

 RATE OUTLOOK

The recent heat wave has brought not only higher temperatures across the country but also higher interest rates.  I guess you could say “careful what you wish for”…we were so tired of the cold, but we were not looking forward to a rate rise.

With the recent Fed rate hike of another .25%, up to 5.5%, it brought Prime Rate to 8.5%.  This is the highest Prime Rate since 1991.  What is Prime Rate?  It is the rate generally used by banks to lend to customers with good credit and is oftentimes used as an index for floating rate loans such as a Home Equity Line of Credit.

Mortgage rates have risen as a result and should level off as we don’t anticipate any more Fed Funds rate hikes.  Recession hopes (or fears) are lessening and a soft landing seems to be on the horizon.  What does that mean for interest rates?  They are likely to ease more slowly than we anticipated earlier in the year.  They will eventually come down, but it may take longer so don’t hold your breath for rates in the 3’s or 4’s again. 

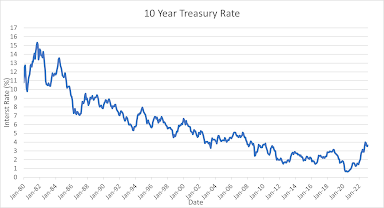
Essentially, we’ve just about hit the average mortgage rates for the last 50 years.  Back when I had to walk miles through the snow to get to school, they were almost identical to today before they shot up in the early 80’s (18%!) and proceeded to generally decline over time from that point until July of 2021.


PROPETY VALUES

While low inventory continues, there is little downward pressure on home prices.  It is now apparent that few homeowners with a rate in the 2’s or 3’s have any motivation to sell, unless they are moving out of state or are experiencing a life change-- (job change, divorce, or death) There are rumors of stagnation in the “luxury” market, i.e. slower pace of selling for homes over $2 to $3 Million. Home prices have risen as of the latest sales in most Southern California markets.

CONSTRUCTION LOANS

Did you know…we have a construction lending department that can provide construction loans for rehab purposes as well as new construction.  They are a bit more complicated as funds are doled out as work is completed and invoices provided, and there is a lot of up-front planning that takes place such as approval of architectural plans, appraisal, contractor, etc.

BEACH TIME and FAMILY UPDATES – Sailing and Swimming!

We recently spent four days camping in Carpinteria on the beach.  We had most of the family there, which was a real treat.  Barbeques, sitting around the campfire, playing in the ocean and on the sand, and taking beach walks in the morning was all part of the experience. We had to watch for the raccoons who were voracious and got away with an entire carton of eggs one evening in our presence!  They are sneaky and fast!

Grandson Theo in San Diego has been killing it in his sailing races.  He just competed in the Jr. National Sabot Championships in Newport at NHYC and came in 19th overall out of 150 sailors.  He was also in the top 10 in the preliminaries.  WOW!  WAY TO GO THEO.

My granddaughter Kay (AKA Karen, my namesake) is age 6 and just finished her very first swim meet and won both her events – the 25 free and 25 fly.  Big surprise as her mama, my partner Katie, was a very competitive swimmer through high school, although college was all about Water Polo. Go Bears!

As always, we are here to help with any questions! 


Monday, September 12, 2022

THAT WAS FAST! Summer is officially over

No more white shoes, white pants or dresses, right?  Although we think that idea is a bit out of date today, at the Yacht Club white pants are not de rigueur after Labor Day.  Acting as the “Officers of the Deck” this week, we were asked to dress in formal yacht club attire which includes white or blue shirts, grey or khaki pants and navy jackets emblazoned with the Club Bullion.

Now, down to business:

Housing Market Correction

The experts are all weighing in on the likelihood of a “correction” to the housing market. Will prices come down?  There is a good deal of downward pressure on prices.  We may see a swing closer to a buyers’ market in the near future.  But remember, inventory is still extremely low.  No “crash” is in sight.  All the factors make it highly unlikely.

Rates

Up, down and sideways. Last week they hit an average of 6% which is the highest since 2008. However, a graph of average interest rates over the last 50 years in the US shows we are still quite near the low end.  It has been the sudden doubling of rates over the last 18 months that has buyers pushing the pause button.  Affordability has decreased with the rate rise.  Loan applications are down significantly which also means there is less competition out there for willing buyers.

Refinance activity particularly has slowed significantly, and is providing only 30% of current total loan volume.

Conforming Loan Limit Increases

The conforming loan limit, which includes both Fannie Mae and Freddie Mac loans, will rise effective January 1st but many lenders, including APM are already accepting rate locks for conforming loans up to a $715,000 loan amount. The actual new limit could be higher, but most agree that $715K is a safe bet.  What does this mean for borrowers?  Conforming loans are easier to qualify for!  Good news all the way around

Down Payment Assistance

No cash for a down payment?  No problem.  We have programs to assist new homebuyers with as little as $500 cash. With a combination of down payment assistance through various programs, coupled with seller credits to offset closing costs, there is almost no cash required to get into a home.  Of course there are income qualification requirements. 

Don't hesitate to reach out to us with questions!  Enjoy the transition to fall, we can't wait to cool off a bit.


Friday, March 27, 2020

Holy Moly! Hang On Tight!

The current environment is unprecedented on many fronts. Quarantines and Social Distancing, unemployment is mounting, and the havoc in the mortgage industry is staggering. Mortgage lenders are under tremendous pressure on multiple fronts: volume, rate drops, market volatility and "churning" of their loan portfolios, e.g. early payoffs and rate lock abandonment. This causes a lack of liquidity since once locked, lenders hedge their positions and if the lock is broken, it is costly. Servicing income drops dramatically and forbearance (forgiveness of loan payments) isn't going to help.

APM is NOT a loan servicer, so we do not face the risks of the large servicing companies or "aggregators" of mortgage loan pools. However we do have interest rate risk, which is the risk of not being able to sell loans, once closed, at low rates if pricing and rates increase.

The Fed move to drop the fed rate did not, and does not directly affect mortgage loan rates. But the stimulus package to buy Mortgage Backed Securities (MBS) DOES have a downward effect on rates. This in reality is NOT helping since it is motivating so many borrowers to break current locks and/or refinance their loans, causing huge losses to the above mentioned servicers/aggregators.

What does it all mean? We all need to be patient, and wait for the markets to normalize. This may take a few weeks or months. In the meantime, The Card Team and APM are diligently working through our pipeline of refinance loans and, as always, prioritizing purchase loans. One of the steps we have taken is locking all refinance loans for 60 days on a 30 day lock price, to handle the high volume.

We are here to answer any questions or concerns you may have. We continue to open new refinance loans for our clients, and prep them for processing, floating the rate and not locking yet, while waiting for the market to settle down.

Thursday, February 21, 2019

5 Tips for your best FICO Score Before You Buy

It is always best to prepare well ahead of time for a home purchase, whether first time or fifth time. We like to begin coaching clients three to six months prior to beginning a home search, to be sure our clients are well-prepared. Your Credit score is extremely important for loan-qualifying purposes, and in order to attain the lowest interest rate.

1. DON'T close any revolving credit accounts; pay them down or off but continue to use them periodically.
2. DON'T pay off any collection accounts; activity in the derogatory section of your credit report can lower your scores. If needed they can be paid through escrow.
3. DO keep all your balances at or below 30% of available credit.
4. DO make all credit card payments on time. A late fee incurred is not reported, unless an account goes 30 days late.
5. DON'T cosign on a loan for someone else. If they miss a payment, your credit will be affected negatively.

Tuesday, March 13, 2018

How Do You Hold Title to Your Home?

There are many ways for individuals, married couples, and multiple parties to hold title to their Real Estate.


Recently an escrow advised me that my married clients were taking title as joint tenants, and I instructed them to please change vesting to Community Property with Right of Survivorship.

Why???? This vesting allows the "basis" in the property, for income tax purposes, to be "stepped-up" as of the date of passing of one of the title holders. It is preferable for all married property owners, unless they have a Living Trust.

A Living Trust is probably the best way to hold title. The primary advantage is to avoid the costs of probate, as all assets in the trust, including real estate, pass directly to the successor trustee and/or beneficiaries without lengthy and expensive legal work. I find that today most of my clients here in California having Living Trusts. Uber important for anyone with children!

Joint Tenancy can be held with anyone else. You can be a joint tenant with a spouse, a mother, brother, father, sister or friend. All owners have equal ownership of the property, and the surviving co-owner(s) automatically own the entire property. Probate is avoided with this form of ownership, but it does not automatically step up the basis in the home for the survivor.

Tenants in Common is a form of ownership for two or more property owners, and the percentage of ownership may be split any way they like. This might be used for unmarried friends or business partners; for families who want to be able to leave their portion of the property to the their heirs, and may be titled in a trust. Each owner may pass their interest to whomever he wants. This is popular with spouses in second marriages, so each spouse can leave their share to their own children. The downside is one of the owners may force a sale of the property, which could be problematic if children of a deceased spouse force the sale of the surviving spouse's home.

I personally hold title to one home in a living trust, and to two others as tenant-in-common. These two are held with other family members at differing percentages. I strongly recommend anyone who owns real estate to consider a Living Trust and I am happy to recommend an Estate and Family Planning attorney.


Thursday, November 30, 2017

LOAN LIMITS RAISED FOR 2018

Conventional loan limits for 2018 have just been announced. They will be $453,100 for lower cost areas, but in high cost counties such as Los Angeles and Orange County, the new limit will be $679,650. This represents a big jump from the current high cost county limit of $636,150. The loan limits for VA loans and FHA loans have not yet been announced, but in 2017 they matched the conventional loan limits.

This is great news for current homeowners who may want to refinance and take advantage of the increased equity in their homes. It is also beneficial for home buyers. Conventional loan programs offer more flexibility vs. jumbo loan programs--in terms of higher debt-to-income ratios and less income documentation. The new loan limits represent increased buying/borrowing power.

Please call me if I can be of assistance! I welcome your questions.

Wednesday, November 15, 2017

Tax Overhaul is Opposed by CAR

The California Association of Realtors has come out vehemently against the proposed changes to our tax code, which would eliminate the tax deduction for state and local taxes, as well as the deduction for mortgage interest for all loans over $500,000. Loans currently held with higher balances (up to $1 million) would be grandfathered in. Further it would eliminate the interest deduction for 2nd home mortgages. Deductible property taxes would be limited to $10,000. According to CAR the average homebuyer in the state would pay an additional $3000 in taxes annually.

Living here in the sunny state where it seldom rains, this would definitely put a dark cloud over the real estate market. Our median home price here in Orange County is $790,000 and in LA County it is $595,000. Already, home affordability rates in Southern California have fallen to the lowest level since 2008 and statewide housing affordability fell to a 10-year low as the tight housing market has driven prices higher and higher. The percentage of California home buyers who can afford a median-priced home in 3rd Q 2017 fell to 28%. These statistics do not apply to condos but to single family homes. Condos are more affordable, and 38% of Californians can afford the $440,000 median-priced condo.

To be clear, all these statistics assume a 20% down payment. With less down (including many first-timers) the affordability is lower...and with more down payment, affordability rises.

But, here in California and other high-price states such as New York, affordability will drop even more if the tax bill goes through as proposed. Real estate values will surely drop as fewer and fewer buyers can afford homes. A recent article in the WSJ notes that in NYC sales are slowing as buyers ponder the effect the tax changes could have to their disposable income.

We always advise clients as to the after-tax consequence of owning a home with a mortgage, and how the interest and RE taxes will provide them with a deduction on their tax return. We'll see!

Tuesday, October 10, 2017

Loans for Self-Employeds

I can't begin to tell you how many times I've had the opportunity to close a home loan for a self-employed individual or family after they have been turned down elsewhere. Maybe it is because I care enough about my clients to take the time to carefully analyze both individual and business tax returns, to understand what their real income is, at least according to standard underwriting practices.

Are there loan programs out there for those who can't qualify with income shown on tax returns? Yes, but they usually rely on deposits either to individual or business bank statements...and they typically require a larger down payment, and carry higher interest rates. Some programs today only require one year's business returns, without averaging income over a two-year period--which helps many.

Any way it works out best for the client, I love solving problems--and seeing them achieve their dream home, or dream loan. Today I am helping an artist who wants to buy a home but doesn't show much income on her tax returns. By eliminating her studio rent, which she she won't need once she is a homeowner, we can attribute more income to her in order to help her qualify for a larger loan.

Sometimes I will completely eliminate a self-employed spouse from the loan application, and just take the W-2 employee in order to qualify. It does take thinking outside the box. And TEAMWORK

!

Tuesday, September 12, 2017

FNMA Relaxes Guidelines

This is great news for both purchase and refinance loans at the conforming loan level, up to $636K in Orange and LA counties.

Updates include:

* Debt-to-income ratios up to 50% from previous 45% max
* Loan to Value for ARM loans up to 95%
* One year's tax returns required for self-employeds
* Disputes on credit report do not need to be removed
* Timeshares now treated as installment debt vs. mortgage loans
* Student loans in deferment or income based payments accepted as reported on credit report
* Alimony payments reduce income vs. being taken as a debt against income
* Mortgages and/or debts paid by others are excluded from debt calculations

These make qualifying for a mortgage much easier for many.

Big news in my office is the new addition to my team of my daughter Katie, who is a loan officer in training. Keeping it all in the family!