American Pacific Mortgage

American Pacific Mortgage
Showing posts with label #mortgageloans. Show all posts

Friday, October 9, 2026

Self-Employed? Don't Assume You Don't Qualify!

 Happy Friday!

One of the questions consumers continue asking Google and AI is:

“I'm self-employed and take a lot of tax deductions. Can I still qualify to buy a home?”

The answer is often YES—but we need to look beyond the obvious.

I've worked with self-employed borrowers for more than 30 years, and one of the biggest misconceptions I encounter is that the income reported on a tax return tells the whole story.

It doesn't always.  And if it does, it can be complicated.

With conventional financing, we analyze the business income, expenses and cash flow. Certain noncash expenses, such as depreciation, may be added back when permitted by underwriting guidelines.  Also home office use, and a couple other items.

When conventional financing doesn't work, we may have other options:

  • Bank-statement loans: Some programs use 12 or 24 months of personal or business deposits, adjusted for applicable expenses, rather than relying on tax-return income.

  • Asset-based qualification: For buyers with substantial eligible assets, certain programs may allow us to use those assets to help establish qualifying income.  There are a variety of formulas that may be used.

  • Non-QM financing: Alternative programs may include P&Ls or qualify based on rental income for an investment property.

Karen's Desk: The Tax Planning Conversation

Here's something I encourage self-employed clients to do: Talk to me before making major tax-planning decisions if purchasing or refinancing a home is on the horizon.

A perfectly legitimate tax strategy that minimizes taxable income may also reduce qualifying mortgage income.This is why collaberation with a Tax or legal professional is always encouraged.

I'm certainly not suggesting anyone pay more taxes than necessary! But coordinating with the borrower's tax adviser before the returns are filed can sometimes preserve more financing options.

Ask Karen

“My buyer has only been self-employed for one year. Should they wait another year before looking?”

Not necessarily!

Conventional guidelines generally look for a two-year history, but there are exceptions for borrowers with at least 12 months of documented self-employment and appropriate prior experience in the same field or occupation.

The important thing is to evaluate the entire situation before telling the buyer they need to wait.

Realtor Talking Point of the Week

When a prospective buyer says, “I'm self-employed, so I probably can't qualify,” try this:

“Don't rule yourself out! I work with a mortgage professional who specializes in self-employed borrowers. Let's have Karen look at your situation before we make assumptions.”

Sometimes the buyer needs a different loan program. Sometimes we need better documentation. And sometimes conventional financing works after all.

AI Prompt of the Week for Realtors

“Write a friendly, 150-word explanation for a self-employed prospective homebuyer who thinks they cannot qualify because of tax deductions. Explain that conventional and alternative mortgage programs evaluate income differently, avoid promising approval, and encourage a conversation with a mortgage professional experienced in self-employed financing.”

One Final Thought

A complicated tax return doesn't necessarily mean a complicated mortgage—or an impossible one.

If you have a self-employed buyer, I'd love to look at their situation early, before they get discouraged or decide to postpone their purchase.

Have a wonderful weekend!

Karen Card
Sr. Loan Officer | NMLS #235218
American Pacific Mortgage Corporation
714-290-6940
www.card-team.com

Monday, August 3, 2026

Dog Days of Summer, Rates and Your Home Equity

 It has been an unquestionably hot summer so far, with no end in sight! Days at the beach or in the pool have provided some of the only respite—along with a cold beverage, perhaps a rosé, a crisp dry white, or an Aperol Spritz. And when I get going on wine, I tend to get a little carried away. 😊

Speaking of wine, we're about to head up to Paso Robles for a little wine tasting, and I'm looking forward to discovering some new Picpouls and Albariños. Yes, Paso has finally caught up and realized its climate is quite friendly to these crisp, mineral-driven whites that are growing in popularity.

Okay, back to business!

The Real Estate Market

The real estate market isn't nearly as hot as the weather.

Mortgage rates have remained stubbornly elevated, and recent geopolitical uncertainty has added another layer of volatility. Meanwhile, affordability continues to be one of the biggest concerns I hear from buyers.

The questions I'm hearing most often are:

"Should I buy now or wait?"

And from homeowners:

"How can I access some of my equity without giving up my low-rate first mortgage?"

Fortunately, there are strategies for both.

Want Your Equity? Meet the HELOC and HELOAN

Homeowners who locked in those wonderful low mortgage rates a few years ago are understandably reluctant to refinance their entire mortgage just to access their equity.

That's where a second mortgage may come in.

A HELOC (Home Equity Line of Credit) is generally a variable-rate line of credit. You can draw funds as needed, repay them, and—during the draw period—typically access the available line again. This can be particularly useful for remodeling projects, unexpected expenses, or situations where you don't need all the money at once.

A HELOAN (Home Equity Loan) is different. It is generally a fixed-rate second mortgage with the proceeds funded at closing. You make payments on that loan separately from your existing first mortgage.

And today's second-mortgage programs aren't necessarily one-size-fits-all.

We have access to some very competitive and interesting options, including:

  • Second mortgages for homeowners who want to preserve a low-rate first mortgage
  • DSCR options for certain rental properties
  • Reverse mortgage second-lien solutions in qualifying circumstances
  • Loan amounts that can reach as high as $4 million, depending on the program and borrower qualifications

Which one makes sense? That depends entirely on what you're trying to accomplish.

Buyers: Let's Solve the PAYMENT Problem

Affordability is absolutely a challenge right now, but that doesn't necessarily mean you should sit on the sidelines.

Rather than focusing exclusively on the interest rate, I like to look at the entire monthly housing expense and ask:

What can we do to make this payment work?

There may be more options than you think.

A seller-paid 2-1 buydown, for example, can substantially reduce the buyer's interest rate and payment during the first two years of the mortgage.

Gift funds from a family member can help with the down payment or closing costs and may reduce the amount that needs to be financed.

And remember, you don't necessarily need 20% down to buy a home. Depending on the loan program and borrower qualifications, down payments can be as low as 3% or 3.5%—and eligible VA borrowers may purchase with 0% down.

Every situation is different. That's where good planning really matters.

Before deciding that you can't afford to buy—or that you need to wait for rates to fall—let's run the numbers and see what's actually possible.

A Real-Life Example

I'm currently working with a family that provides a perfect example of how these strategies can come together.

The parents have built substantial equity in their home, and now they'd like to use some of that equity to help their adult son purchase his first home.

We're looking at the entire picture: how much equity to access, the best way to access it, how much the parents should contribute, and how to structure the son's financing so that his new monthly payment remains comfortable.

I love these transactions because we're not simply arranging a mortgage. We're helping one generation use the wealth they've created through homeownership to give the next generation a head start.

If you've ever thought about helping a child or grandchild purchase a home, let's talk. There may be several ways to structure it.

Don't Forget About 1031 Exchanges

One last reminder for my real estate investors:

Before you sell an investment property, talk to us about a 1031 exchange.

A properly structured 1031 exchange may allow you to defer capital gains taxes by exchanging qualifying investment real estate for another qualifying property.

We have excellent resources for both 1031 exchange advice and accommodation, and timing is critical. The conversation should happen before the sale closes, not afterward.

If you're considering selling an investment property, please call me early in the process so we can connect you with the appropriate professionals.

As Always...

Whether you're thinking about buying, refinancing, accessing equity, helping your children purchase their first home, or simply wondering what your options are in today's market, I'm always happy to talk through the numbers.

Sometimes the answer is a new loan.

Sometimes it's keeping exactly what you have.

The important thing is knowing the difference.

Enjoy the rest of your summer—and I'll report back on the Paso Albariños! 🍷

Karen Card
The Card Team

Saturday, July 11, 2026

What Buyers are Really Asking; Divorce & Life Transitions

Every week I spend time researching the questions buyers are asking Google and ChatGPT before they ever contact a Realtor or lender. My goal is to keep you informed about what your clients are thinking—and to help you answer their questions with confidence.

This Week's Focus: Divorce & Life Transitions

Divorce is one of life's most challenging transitions, and for many people, their home is their largest asset. Unfortunately, one of the biggest mistakes I see is waiting until the divorce is finalized before discussing mortgage financing.

By then, some opportunities may already have been lost.

Here are some of the questions borrowers are asking AI this week:

"Can I keep the house after my divorce?"

Possibly—but the answer depends on much more than simply wanting to keep it.

Can the remaining spouse qualify on their own? Will support income be received, and can it be used for qualification? Is refinancing necessary? These questions should be addressed early in the process, not after the settlement agreement has been signed.

"Does the divorce decree remove me from the mortgage?"

No.

A divorce decree determines who is responsible for the home as part of the legal settlement, but it does not automatically remove a borrower from the mortgage loan. In many cases, refinancing or another approved solution is needed before one spouse is released from liability.  However, this loan will not be considered for the spouse who is  not responsible for the loan, when purchasing a new home.

"Can support income help me qualify?"

Often, yes.

Depending on the loan program and documentation, alimony or child support income may be considered for qualification. The timing, documentation, and history of those payments can make a significant difference.  Typically six months of receipt is required in order to use it.

"Can I buy another home before my divorce is final?"

Sometimes.

Every situation is unique. Factors such as qualifying income, existing mortgage obligations, the terms of the separation agreement, and available assets all play an important role. This is one reason it's so valuable to begin planning early.  I’ve handled these situations before, and so long as there is a court approved property division agreement, it is possible.

Karen's Loan Desk

One of the most rewarding parts of my job is helping clients through major life transitions.

I've worked with many individuals before, during, and after a divorce. While every situation is different, I've learned that the earlier we have the mortgage conversation, the more options we usually have.

Sometimes it's not about finding a loan—it's about creating a strategy that supports the best possible outcome for everyone involved.

The takeaway?

Don't wait until the divorce is final to discuss financing. A conversation early in the process can help avoid surprises and preserve valuable options.

AI Prompt of the Week for Realtors

One of the best ways to use ChatGPT is to communicate with empathy while providing helpful information. Copy and paste this prompt:

Act as an experienced Orange County Realtor. Write a compassionate email to someone going through a divorce who may be concerned about their housing options. The email should be reassuring, educational, and non-salesy. Explain why it's important to speak with a mortgage professional early in the process to understand financing options before major decisions are finalized. End with a gentle invitation to ask questions. Keep it under 300 words.

Realtor Tip of the Week

If you have clients navigating a divorce, separation, or another major life transition, let's have a conversation before the property is listed, refinanced, or awarded in the settlement.

A simple planning session can help answer important questions, identify potential challenges, and give your clients greater confidence as they move forward.

As always, I'm happy to review any scenario, answer questions, or help develop a financing strategy that best serves your clients.

Have a wonderful weekend!

 Karen and the Card Team

Wednesday, October 4, 2023

ADVERSITY, OPPORTUNITY AND FAST CASH!


MARKET UPDATE - ADVERSITY

The latest news for multi-family housing is developers have slowed/stopped new construction.  This is primarily due to higher interest rates coupled with greater difficulty qualifying for loans.  This will translate into higher rents, particularly in the coastal areas of California where housing is already in short supply and high demand.

Translation:  Prospective buyers should not wait for rates or prices to come down, as neither is likely in the next 12 months.  No one anticipates home values to decrease.

OPPORTUNITIES

We are offering a personal loan program – NOT a Mortgage loan – for auto loans, remodels, swimming pools, debt consolidation, recreation and more.  This is not recorded on your home and has no effect on the low rate first mortgage most of our clients have. The turn time on these loans is extremely short, even overnight, and offers a quick and easy way to access fast cash.

Loan amounts can vary from $5,000 to $100,000.  Loans are underwritten based on income, assets, and credit.  The process is completely digital and there are no up-front fees or prepayment penalties.

Click here for the link to a quick qualification process:  Personal Loan Link

REMINDERS

Real estate taxes are coming due, and must be paid by December 10th to avoid penalties  The second half taxes are due by April 10th.  Such great timing for Christmas and tax time, huh?

Self-employed borrowers should have their taxes reviewed by us prior to filing if they are considering making a home purchase or refinance in the next two years.  Writing off too many expenses can kill a home purchase or refi, unless you want to use a bank statement loan which carries a higher rate.

PERSONAL UPDATES

I’m writing this from Madera (just north of Fresno)  where I am temporarily staying with my sister who suffered a stroke.  My sister lives alone and we were extremely lucky her daughter sounded the alarm when she could not contact her one morning. 


She is improving daily, and we expect a full recovery.  This has been a big wakeup call and reminder to be grateful every day, keep your loved ones close, always do your best and be kind to all.  And, take good care of your health.

As always, call us with any questions or concerns.


Monday, August 7, 2023

HOT, MUGGY HEAT WAVE AND RATE HIKES

 RATE OUTLOOK

The recent heat wave has brought not only higher temperatures across the country but also higher interest rates.  I guess you could say “careful what you wish for”…we were so tired of the cold, but we were not looking forward to a rate rise.

With the recent Fed rate hike of another .25%, up to 5.5%, it brought Prime Rate to 8.5%.  This is the highest Prime Rate since 1991.  What is Prime Rate?  It is the rate generally used by banks to lend to customers with good credit and is oftentimes used as an index for floating rate loans such as a Home Equity Line of Credit.

Mortgage rates have risen as a result and should level off as we don’t anticipate any more Fed Funds rate hikes.  Recession hopes (or fears) are lessening and a soft landing seems to be on the horizon.  What does that mean for interest rates?  They are likely to ease more slowly than we anticipated earlier in the year.  They will eventually come down, but it may take longer so don’t hold your breath for rates in the 3’s or 4’s again. 

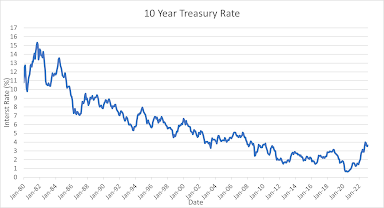
Essentially, we’ve just about hit the average mortgage rates for the last 50 years.  Back when I had to walk miles through the snow to get to school, they were almost identical to today before they shot up in the early 80’s (18%!) and proceeded to generally decline over time from that point until July of 2021.


PROPETY VALUES

While low inventory continues, there is little downward pressure on home prices.  It is now apparent that few homeowners with a rate in the 2’s or 3’s have any motivation to sell, unless they are moving out of state or are experiencing a life change-- (job change, divorce, or death) There are rumors of stagnation in the “luxury” market, i.e. slower pace of selling for homes over $2 to $3 Million. Home prices have risen as of the latest sales in most Southern California markets.

CONSTRUCTION LOANS

Did you know…we have a construction lending department that can provide construction loans for rehab purposes as well as new construction.  They are a bit more complicated as funds are doled out as work is completed and invoices provided, and there is a lot of up-front planning that takes place such as approval of architectural plans, appraisal, contractor, etc.

BEACH TIME and FAMILY UPDATES – Sailing and Swimming!

We recently spent four days camping in Carpinteria on the beach.  We had most of the family there, which was a real treat.  Barbeques, sitting around the campfire, playing in the ocean and on the sand, and taking beach walks in the morning was all part of the experience. We had to watch for the raccoons who were voracious and got away with an entire carton of eggs one evening in our presence!  They are sneaky and fast!

Grandson Theo in San Diego has been killing it in his sailing races.  He just competed in the Jr. National Sabot Championships in Newport at NHYC and came in 19th overall out of 150 sailors.  He was also in the top 10 in the preliminaries.  WOW!  WAY TO GO THEO.

My granddaughter Kay (AKA Karen, my namesake) is age 6 and just finished her very first swim meet and won both her events – the 25 free and 25 fly.  Big surprise as her mama, my partner Katie, was a very competitive swimmer through high school, although college was all about Water Polo. Go Bears!

As always, we are here to help with any questions! 


Monday, September 12, 2022

THAT WAS FAST! Summer is officially over

No more white shoes, white pants or dresses, right?  Although we think that idea is a bit out of date today, at the Yacht Club white pants are not de rigueur after Labor Day.  Acting as the “Officers of the Deck” this week, we were asked to dress in formal yacht club attire which includes white or blue shirts, grey or khaki pants and navy jackets emblazoned with the Club Bullion.

Now, down to business:

Housing Market Correction

The experts are all weighing in on the likelihood of a “correction” to the housing market. Will prices come down?  There is a good deal of downward pressure on prices.  We may see a swing closer to a buyers’ market in the near future.  But remember, inventory is still extremely low.  No “crash” is in sight.  All the factors make it highly unlikely.

Rates

Up, down and sideways. Last week they hit an average of 6% which is the highest since 2008. However, a graph of average interest rates over the last 50 years in the US shows we are still quite near the low end.  It has been the sudden doubling of rates over the last 18 months that has buyers pushing the pause button.  Affordability has decreased with the rate rise.  Loan applications are down significantly which also means there is less competition out there for willing buyers.

Refinance activity particularly has slowed significantly, and is providing only 30% of current total loan volume.

Conforming Loan Limit Increases

The conforming loan limit, which includes both Fannie Mae and Freddie Mac loans, will rise effective January 1st but many lenders, including APM are already accepting rate locks for conforming loans up to a $715,000 loan amount. The actual new limit could be higher, but most agree that $715K is a safe bet.  What does this mean for borrowers?  Conforming loans are easier to qualify for!  Good news all the way around

Down Payment Assistance

No cash for a down payment?  No problem.  We have programs to assist new homebuyers with as little as $500 cash. With a combination of down payment assistance through various programs, coupled with seller credits to offset closing costs, there is almost no cash required to get into a home.  Of course there are income qualification requirements. 

Don't hesitate to reach out to us with questions!  Enjoy the transition to fall, we can't wait to cool off a bit.


Friday, March 27, 2020

Holy Moly! Hang On Tight!

The current environment is unprecedented on many fronts. Quarantines and Social Distancing, unemployment is mounting, and the havoc in the mortgage industry is staggering. Mortgage lenders are under tremendous pressure on multiple fronts: volume, rate drops, market volatility and "churning" of their loan portfolios, e.g. early payoffs and rate lock abandonment. This causes a lack of liquidity since once locked, lenders hedge their positions and if the lock is broken, it is costly. Servicing income drops dramatically and forbearance (forgiveness of loan payments) isn't going to help.

APM is NOT a loan servicer, so we do not face the risks of the large servicing companies or "aggregators" of mortgage loan pools. However we do have interest rate risk, which is the risk of not being able to sell loans, once closed, at low rates if pricing and rates increase.

The Fed move to drop the fed rate did not, and does not directly affect mortgage loan rates. But the stimulus package to buy Mortgage Backed Securities (MBS) DOES have a downward effect on rates. This in reality is NOT helping since it is motivating so many borrowers to break current locks and/or refinance their loans, causing huge losses to the above mentioned servicers/aggregators.

What does it all mean? We all need to be patient, and wait for the markets to normalize. This may take a few weeks or months. In the meantime, The Card Team and APM are diligently working through our pipeline of refinance loans and, as always, prioritizing purchase loans. One of the steps we have taken is locking all refinance loans for 60 days on a 30 day lock price, to handle the high volume.

We are here to answer any questions or concerns you may have. We continue to open new refinance loans for our clients, and prep them for processing, floating the rate and not locking yet, while waiting for the market to settle down.

Thursday, April 4, 2019

Real Estate in California...What 's Next?

It is that time of year, again...Spring buying season. Home listings are growing in numbers, but where are the buyers? Most homes are sitting on the market longer than in the past few years, and most are selling below list price. We expect activity to pick up, since rates have adjusted down nicely. Most economists see home values flattening out somewhat, but we aren't expecting any drops in value in the near term.
Rates are also flattening out, and we've seen a couple of moments of the dreaded "inverted" yield curve which means that short term rates rise above longer-term rates. This translates to a couple of things: 1. A recession is expected sooner than later, and 2. the marketplace sees more risk in the short term vs. the long term.

What does this mean for you? If you are interested in buying, now is the time to jump while rates remain near historical lows.

We believe Reverse loans are going to continue to gain in popularity due to the aging baby-boomer population. These increase the buying power of a buyer over age 62 when coupled with cash toward the purchase price. They are also very useful for those wishing to retire existing debt on their home to reduce monthly expenditures, or to have a line of credit to use when future needs arise, all without a required monthly payment.

ON THE HOME FRONT

The first quarter has sped by with alarming speed! My grandchildren are growing like weeds, and entertaining us endlessly. They are now six, four, two, one and almost one. WOW! Steve is still commuting to Dallas, but we expect that to wind down this year. My daughter is working with me here at THE CARD TEAM, and we are having a lot of fun and keeping very busy!

We are busier than ever. Between kids, grandkids, Yacht Club events, work and exercise there isn't much downtime. We have also taken up golf, and try to get out on weekends when the weather is nice. Steve is going to crew in the Newport-Ensenada race for the first time and I will cheer from the sidelines when I am not on a wine tasting tour of the wineries near there. We have some scuba diving planned for the year both locally, in Catalina, and in Hawaii later in the year. A camping trip to El Capitan (north of Santa Barbara) is on the books for September, with all our kids and grandkids. It will be wild! When we are all together it is sort of like a tsunami, but always filled with laughter and good times.

Last year we took a couple of scuba trips, one to Cozumel and one to Cabo Pulmo outside Cabo San Lucas. The trip to Cabo Pulmo was combined with some fishing in the Sea of Cortez with a large group of friends, which was a blast. Nothing we caught was big enough to write home about, but it made some for very good eating for ceviche and sashimi. We also went up to our favorite family vacation spots in the High Sierra at Rock Creek for five days with all the family. All fun: lots of hiking, fishing, laughing and card games. In between all that we took quick trips to Catalina, Palm Springs and La Quinta. Phew!

We are looking forward to another fabulous year and wish you the same! Remember, we create experiences that matter.